
Inventory Accounting ( Accounting for inventory ) is a term for the systems and methods used to track, value, and report a company’s stock of goods. Inventory is a current asset on the balance sheet and includes raw materials, work-in-progress, and finished goods held for sale.
The value of inventory is critical because it directly impacts a company’s financial statements and profitability.
In today’s fast-paced supply chains, outdated one-size-fits-all approaches no longer cut it. Creative management techniques—like seasonal cost layering or gamified cycle counts—empower businesses to stay agile, reduce shrinkage, and uncover hidden efficiencies.
In This Guide, You’ll Discover
Key strategies, proven methods, and actionable steps to optimize inventory accounting and boost profitability.
- The importance of inventory accounting
- The core principles behind inventory as both an asset and a cost
- Proven valuation methods — plus innovative twists to maximize tax and cash-flow benefits
- Practical controls, analytics dashboards, and incentive programs to keep your teams aligned
- A step-by-step roadmap (with ready-to-use templates) that turns complex accounting tasks into clear, actionable steps
Get ready to transform your inventory from a static line on the balance sheet into a dynamic driver of growth.
Importance of Inventory Accounting
Accurate inventory accounting shines a light on the true cost of holding stock—and the potential losses when things go missing.
- High Carrying Costs: Inventory carrying (or holding) costs typically consume 20 %–30 % of the total inventory value each year, covering financing, storage, insurance, obsolescence and handling expenses. In practical terms, a business holding $100 000 of inventory will spend $20 000–$30 000 annually simply to keep that stock on the shelf ( Opensend Investopedia ).
- Rising Global Shrinkage: Retail shrinkage (losses from theft, damage, or administrative error) is soaring. In 2024, worldwide retail shrink is projected to hit $132 billion, up from $112 billion in 2022—a 17.9 % increase in just two years ( InVue ).
- Growing Shrink Rates: The average retail shrink rate climbed to 1.6 % of sales in 2023, up from 1.4 % in 2022, according to the National Retail Federation’s latest security survey ( Teamwork Commerce ).
By implementing rigorous inventory accounting—cycle counts, variance analysis, and real‐time valuation—businesses can uncover hidden carrying costs, pinpoint shrinkage hotspots, and deploy targeted controls to reclaim tens of thousands (or even millions) in annual savings.

Inventory Accounting Systems
There are two primary systems for tracking inventory:
- Perpetual System: This system continuously updates inventory records in real-time as items are bought and sold. It provides an up-to-the-minute view of inventory levels and the cost of goods sold (COGS).
- Periodic System: This system updates inventory at specific intervals, typically at the end of an accounting period. It requires a physical count of the inventory on hand to determine the ending

Core Concepts of Accounting for Inventory
Effective accounting for inventory begins with mastering a few foundational ideas. This deep-dive will help you understand how inventory moves through your books, why it matters, and which metrics keep you on track.
1. Inventory: Asset Today, Expense Tomorrow
- On the Balance Sheet: Inventory sits under Current Assets, representing money you’ve tied up in stock.
- On the Income Statement: When you sell goods, that asset “becomes” Cost of Goods Sold (COGS). Accurate accounting for inventory ensures your profit margins and tax obligations are correct.
Pro tip: Track every cost—purchase price, freight-in, duties, handling—so your ending inventory value reflects your true investment.
2. The Cost-Flow Cycle Explained
- Beginning Inventory: What’s left over from the prior period.
- Purchases (and Production Costs): All costs to bring new inventory in.
- Goods Available for Sale = Beginning Inventory + Purchases
- Ending Inventory: Physical count or system value at period-end.
- COGS Calculation: COGS = Beginning Inventory + Purchases − Ending Inventory
Mastering this cycle is the heart of inventory accounting, linking your stock movements to financial results.
3. Matching Principle & System Choices
- Matching Principle: Align your inventory costs with the revenue they generate in the same reporting period.
- Periodic vs. Perpetual Systems:
- Periodic: Manual counts at set intervals—low tech, higher risk of discrepancies.
- Perpetual: Real-time updates via barcode or ERP—better accuracy, immediate insights.
Action step: If you still use a periodic system, consider a hybrid—monthly counts with spot checks—to boost visibility without a huge tech investment.
4. Key Metrics to Measure Success
These are three important metrics for analyzing how efficiently a company manages its inventory. Here are the formulas and what they mean in simple terms.
1. Inventory Turnover Ratio
The Inventory Turnover Ratio measures how many times a company sells and replaces its inventory over a period.
Breaking Down the Components:
- Cost of Goods Sold (COGS): Direct costs for producing goods or services sold. Found on the income statement.
- Average Inventory: Provides a better period representation than ending inventory.
$$\text{Average Inventory} = \frac{\text{Beginning Inventory} + \text{Ending Inventory}}{2}$$
In simple terms: A higher number means you are selling your products faster. A high turnover is good because it means you have less cash tied up in inventory and are selling goods efficiently.
2. Days Sales of Inventory (DSI)
Days Sales of Inventory (DSI), also known as Days in Inventory, measures the average number of days it takes for a company to turn its inventory into sales.
In simple terms: A lower DSI is better because it means it takes fewer days to convert inventory into sales. This suggests efficient inventory management and strong demand for the products.
3. GMROI (Gross Margin Return on Investment)
GMROI (Gross Margin Return on Investment) shows the amount of gross profit generated for every dollar invested in inventory.
In simple terms: A higher GMROI is desirable because it tells you that your company is generating more profit for each dollar of inventory cost. This is a powerful metric for evaluating the profitability of your inventory investments.
5. Quick Wins for Stronger Controls
- Regular Reconciliation: Match counts to system records weekly or monthly.
- Clear Cutoff Policies: Define how and when to record freight, returns, or consigned goods.
- Document Everything: Keep purchase invoices, shipping docs, and adjustment logs organized.
By embedding these core concepts into your operations, you lay the groundwork for streamlined, accurate, and CashFlow-optimized accounting for inventory that supports growth, profitability, and compliance.

Valuation Methods & Innovative Twists in Inventory Accounting
When it comes to inventory accounting, the valuation method you choose can dramatically affect your financial statements, tax liabilities, and cash flow. Below, we explore both standard approaches and creative adaptations that savvy businesses use to align cost recognition with real-world operations.
Understanding the Core Methods
- FIFO (First-In, First-Out)
Under FIFO, the oldest inventory costs hit Cost of Goods Sold (COGS) first. In an inflationary climate, FIFO typically shows lower COGS and higher reported profits—helpful if you want to present strong earnings, but it can lead to higher taxes. - LIFO (Last-In, First-Out)
LIFO assumes the newest stock sells first, so COGS reflects current, higher costs. That reduces taxable income during rising-cost periods. Note that LIFO is disallowed under IFRS, so it’s only an option for U.S. GAAP filers. - Weighted Average Cost
This method smooths out price swings by dividing total cost by total units. It’s ideal for homogeneous products (like chemicals or grains) where individual tracking isn’t practical. - Specific Identification
When each item carries a unique cost—think serialized machinery or bespoke jewelry—specific identification tracks exact costs to each sale, yielding pinpoint accuracy but requiring rigorous record-keeping.
Going Beyond Basics: Creative Twists
Traditional methods serve most needs, but hybrid approaches can unlock further advantages:
Seasonal Cost Layering
- Why it matters: Retailers and manufacturers often face sharp cost swings between peak and off-peak seasons.
- How to apply:
- Segment purchases into “peak” and “off-peak” buckets (e.g., Q3 vs. Q1).
- Apply FIFO within each bucket, so high-season goods carry high-season costs.
- Impact: Matches sales revenue with the most relevant cost basis, smoothing profit volatility and improving forecast accuracy.
Lot-Based Dynamic Averaging
- Why it matters: You need more precision than a global average but can’t track every single unit.
- How to apply:
- Assign costs per lot when goods are received.
- Calculate an average per lot, then use that lot’s average when items are sold.
- Impact: Balances administrative effort with improved cost matching—ideal for batch-oriented operations.
Real-World Example: Fashion Ecommerce
A mid-sized apparel retailer saw fabric costs swing by 30% between spring and fall collections. Using plain FIFO, profits spiked in spring then plunged later, confusing investors and complicating cash forecasts.
- Solution: Implemented seasonal cost layering, treating each collection as its own cost pool.
- Result: Spring and fall P&Ls now reflect true margin dynamics, enabling more accurate pricing and inventory replenishment plans.
Actionable Steps to Innovate Your Valuation
- Audit Your Cost Variance
Pull 12 months of purchase data to quantify cost swings—identify if you have seasonal, batch, or random fluctuations. - Choose a Base Method
Select FIFO, LIFO (if permitted), weighted average, or specific identification as your foundation. - Pilot a Hybrid Model
Run your accounting system in parallel: standard vs. hybrid approach for one quarter. Compare COGS, taxes, and ending inventory valuation. - Document & Train
Update your accounting manual with clear policies. Host a brief workshop for finance and warehouse teams to ensure consistent application. - Monitor & Refine
Review key metrics—inventory turnover, gross margin ratio, DSI—monthly to verify the hybrid model delivers the intended benefits.
By thoughtfully combining the best practices with innovative twists, you not only optimize taxes and profits but also gain sharper insights into your business rhythms—turning inventory valuation from a compliance task into a strategic advantage.
Robust Controls, Precise Counts & Real-Time Analytics in Inventory Accounting
Effective inventory accounting isn’t just about valuation—it’s about control. By designing strong counting processes and leveraging analytics, you prevent shrinkage, eliminate errors, and gain actionable insights.
1. Designing a Risk-Based Cycle Count Program
- Identify High-Risk SKUs:
- Use Pareto analysis to find the 20 % of items that drive 80 % of value.
- Tag these as “priority” for more frequent counts.
- Set Count Frequencies by Risk:
- High-Value/High-Volatility Items: Weekly or biweekly counts.
- Mid-Tier Items: Monthly cycle counts.
- Low-Value/Stable Items: Quarterly counts.
2. Choosing Between Periodic vs. Perpetual Count Systems
- Periodic Counting
- Pros: Low tech, minimal upfront cost.
- Cons: Blind spots between counts; larger reconciliation at period end.
- Perpetual Counting
- Pros: Real-time inventory balances; immediate COGS updates; better data for forecasting.
- Cons: Requires barcode/RFID infrastructure and system integration.
- Hybrid Approach
- Combine weekly perpetual updates for fast movers with monthly physical cycle counts for verification on slower SKUs.
Action Step: If you lack a full ERP, start with handheld barcode scanners and integrate counts overnight into your accounting system.
3. Building Real-Time Analytics Dashboards
- Key Metrics to Track
- Inventory Accuracy Rate
The Inventory Accuracy Rate measures how well your recorded inventory matches the actual physical count.$$\text{Inventory Accuracy Rate} = \frac{\text{System Quantity}}{\text{Counted Quantity}} \times 100$$Explanation:
- System Quantity: The quantity recorded in your inventory management system.
- Counted Quantity: The actual physical quantity counted during stocktaking.
- Multiplying by 100 converts the ratio into a percentage for easier interpretation.
In simple terms: This tells you the percentage of your inventory records that are correct. A higher percentage is better, as it means your inventory tracking system is reliable. - Shrinkage Rate
The Shrinkage Rate calculates the percentage of inventory that is lost or unaccounted for. This can be due to theft, damage, or administrative errors.$$\text{Shrinkage Rate} = \frac{\text{System Quantity} – \text{Counted Quantity}}{\text{System Quantity}} \times 100$$Explanation:
- System Quantity: The quantity recorded in your inventory system before stocktake.
- Counted Quantity: The actual quantity found during physical count.
- Subtracting the counted quantity from the system quantity gives the loss amount. Dividing by system quantity and multiplying by 100 expresses the loss as a percentage.
In simple terms: This metric shows you what percentage of your inventory has gone missing. A lower percentage is always the goal, as it indicates fewer losses.
- Inventory Accuracy Rate
- Dashboard Essentials
- Overview Tile: Current accuracy vs. target (e.g., 99 %).
- Trend Chart: Accuracy and shrinkage rates over the past 6 months.
- SKU Drill-Down: Top 10 SKUs by variance—helps pinpoint problem areas.
- SEO Tip: Optimize image alt text for any dashboard screenshots with “accounting for inventory dashboard.”
Pro Tip: Use built-in BI tools in your ERP (e.g., Odoo, NetSuite) or Invenory Management Software (Zoho Inventory, Cash Flow Inventory) to automate data pulls and visualizations.
4. Actionable Steps to Strengthen Controls & Analytics
- Map Your Process: Document how goods move from receipt through picking, counting, and sale. Identify where errors most often occur.
- Implement Barcode/RFID: Even simple barcode labels cut counting time by 50 % and reduce mis-scans.
- Automate Alerts: Set notifications for negative on-hand balances or large variances post-count.
- Review & Adjust: Hold a monthly “count review” meeting—surface trends, update count frequencies, and refine your control policies.
By embedding risk-based controls, choosing the right counting system, and leveraging real-time analytics, your accounting for inventory becomes a proactive discipline—minimizing shrinkage, maximizing data accuracy, and empowering smarter business decisions.
Preventing Shrinkage & Engaging Teams in Inventory Accounting
Shrinkage—whether from theft, damage, or data errors—erodes profit margins and undermines the integrity of your inventory accounting. To combat it, you need both strong process controls and a motivated team. Here’s how to build a culture of accuracy and accountability.
1. Strengthen Physical Security & Process Controls
- Zoned Access & Sign-In Logs
Break your warehouse into controlled zones (receiving, storage, picking). Require badge scans or sign-in sheets for each zone entry. This adds a deterrent to unauthorized access. - Double-Verification for High-Value Items
For SKUs above a threshold (e.g., > $1,000 per unit), mandate two-person counts and dual sign-offs on adjustments. This “four-eyes” approach drastically cuts error rates. - Damage-Reporting Workflows
Integrate a simple mobile form for warehouse staff to log damaged goods immediately—capturing SKU, quantity, and photo. Automate alerts to finance so adjustments get recorded in inventory accounting without delay.
2. Gamify Accuracy & Build Ownership
- Team Scoreboards
Publish weekly “count accuracy” scores on a digital dashboard in the break room. Celebrate teams that hit targets (e.g., >99.5% accuracy) with small rewards—coffee gift cards or an extra lunch break. - Count-athon Events
Host quarterly “Count-athons” where teams compete to spot discrepancies fastest. Offer prizes like branded swag to foster friendly competition and reinforce best practices.
3. Empower Through Training & Ownership
- Onboarding Bootcamp
New hires undergo a “Shrinkage 101” module: hands-on barcode scanning drills, mock counts, and sessions on why accurate counts feed into clean financial statements. - Cross-Functional “Inventory Champions”
Nominate one person per shift to be the go-to for count questions. They audit one random SKU daily, coach peers on scan procedures, and escalate anomalies.
4. Continuous Feedback & Improvement
- Monthly Shrinkage Reviews
Finance and operations meet to review shrinkage trends by zone and SKU. Use these insights to tweak controls, retrain teams, or adjust security protocols. - Recognition & Feedback Loop
Share success stories in company newsletters (“Team Z reduced shrinkage by 40% this quarter!”) and solicit frontline ideas—often the best prevention tactics come from those on the warehouse floor.
By embedding robust controls, gamification, and ongoing training into your accounting for inventory processes, you’ll minimize shrinkage, boost morale, and transform what was once a compliance chore into a shared mission for accuracy and profit protection.
Tax & Compliance Optimization in Inventory Accounting
Navigating the tax and regulatory landscape is a critical facet of inventory accounting. The choices you make—from valuation methods to write-down practices—directly affect your tax bill and audit footprint. This deep dive covers strategies to optimize liabilities while staying audit-ready.
1. Choosing the Right Valuation Method for Tax Efficiency
- FIFO vs. LIFO Implications
- FIFO (First-In, First-Out) often yields higher profits—and higher taxes—in inflationary times because older, lower costs hit COGS first.
- LIFO (Last-In, First-Out) pushes newer, higher costs into COGS, reducing taxable income when prices rise. Note: LIFO is allowed under U.S. GAAP but prohibited under IFRS.
- Weighted Average & Specific ID
- Weighted Average smooths out cost spikes but can obscure tax planning opportunities.
- Specific Identification offers pinpoint cost matching—useful for luxury or custom items where precise tax treatment (e.g., capital vs. ordinary income) matters.
2. Strategic Write-Downs & Obsolescence Reserves
- When to Write Down Inventory
- Write down inventory when net realizable value (NRV) falls below cost—common for perishables, tech, or fashion lines.
- Timely write-downs lower taxable income in the period they occur.
- Setting Up Obsolescence Reserves
- Estimate future write-offs for slow movers or obsolete stock.
- Record as a contra-asset reserve: smooths P&L impact and pre-emptively reduces tax base.
Pro Tip: Document your NRV methodology (sampling, market data) in your accounting manual to satisfy auditors.
3. IFRS vs. GAAP: Key Compliance Differences
| Topic | U.S. GAAP | IFRS |
|---|---|---|
| LIFO Method | Permitted | Prohibited |
| Lower of Cost or NRV | Lower of Cost or Market (LCM) | Lower of Cost or NRV |
| Reversal of Write-Downs | Not allowed | Allowed if conditions improve |
| Disclosure Requirements | Cost-flow method & COGS impact | Additional qualitative disclosures |
Action Step: If you operate internationally, maintain dual records or use an IFRS-compliant sub-ledger to avoid downstream reconciliation headaches.
4. Transfer Pricing & Multi-Jurisdictional Considerations
- Intercompany Inventory Transfers
- Document transfer prices at arm’s-length to satisfy tax authorities.
- Use the Comparable Uncontrolled Price (CUP) method for high-value goods when possible.
- Customs Valuation
- Ensure your declared import value matches your internal cost basis to avoid fines and customs adjustments.
Best Practice: Centralize transfer-pricing documentation in a single file—include policy, benchmark studies, and intercompany invoices—for efficient audit responses.
5. Audit-Ready Documentation & Controls
- Standardized Policy Manual
- Clearly define your chosen valuation methods, write-down triggers, and reserve calculations.
- Automated Workflow Logs
- Track every inventory adjustment (receipts, transfers, write-downs) with timestamped approvals in your ERP.
- Regular Compliance Reviews
- Schedule quarterly internal audits: verify NRV assessments, transfer-pricing entries, and reserve adequacy.
6. Quick Action Checklist
- Evaluate Valuation Method: Run a tax-impact simulation for FIFO vs. LIFO vs. average cost.
- Formalize NRV & Reserve Policy: Document and date your obsolescence methodology.
- Harmonize IFRS/GAAP Records: Implement sub-ledgers or parallel reporting for international ops.
- Centralize Transfer-Pricing Docs: Maintain a living file of intercompany pricing studies.
- Automate Approval Logs: Enable role-based workflows in your accounting system for all inventory adjustments.
By proactively optimizing your inventory accounting from a tax and compliance standpoint, you reduce liabilities, smooth earnings volatility, and stand audit-ready—turning regulatory requirements into strategic opportunities.
Linking Inventory Accounting to Cash Flow
Understanding accounting for inventory isn’t just about valuing stock—it’s essential for accurate cash-flow forecasting and working-capital management. Here’s how to turn inventory data into reliable cash insights.
Forecast Cash Requirements with Inventory KPIs
1. Days Sales of Inventory (DSI)
The Days Sales of Inventory (DSI) tells you the average number of days it takes to sell your inventory.
What it means: A high DSI indicates that your inventory is sitting on the shelves for a long time. This is a problem because it means more of your company’s cash is tied up in stock, which could be used elsewhere. If your DSI is high, you should plan your finances and payment terms with suppliers to account for this slow-moving cash.
2. Inventory Turnover Ratio
The Inventory Turnover Ratio measures how many times your company sells and replaces its inventory over a period.
What it means: A low turnover ratio is a warning sign of potential overstocking. It suggests that you are not selling your inventory as quickly as you are buying it. This can lead to increased costs for storage and insurance, as well as the risk of products becoming outdated. You can use this insight to adjust your purchasing schedules and avoid these excess carrying costs.
Action Tip: Integrate these metrics into your monthly cash-flow model. When DSI spikes, model the additional days of payables needed or consider short-term financing for peak inventory build-ups.
2. Align Purchase Timing with Cash Cycles
- Just-in-Time (JIT) Ordering
Synchronize orders so inventory arrivals match production or sales—minimizes holding costs and smooths cash outlays. - Vendor-Managed Inventory (VMI)
Shift ordering responsibility to suppliers. You only pay for inventory as it’s consumed, improving free cash flow.
3. Leverage Consignment & Drop-Ship Models
- Consignment Stock
Inventory sits on your premises but remains owned by the supplier until sold. No upfront cash outlay—enhances liquidity. - Drop-Shipping
Suppliers ship directly to customers. Inventory never touches your balance sheet, vastly reducing working-capital needs.
Pro Insight: Combine consignment with real-time accounting for inventory entries to track availability without impacting cash.
4. Integrate Inventory Accounting into Cash-Flow Statements
- Adjust Operating Cash Flow
- Add back non-cash inventory write-downs.
- Subtract increases in inventory as a use of cash.
- Project Future Outflows
- Use your turnover and DSI targets to forecast next quarter’s inventory purchases.
- Link to payables terms—for example, 30-day net terms mean you’ll pay two weeks after receipt.
Practical Template: Build a three-statement model where ending inventory from your balance sheet feeds into COGS on the income statement and inventory changes flow through to operating cash flow.
5. Quick-Start Guide to Syncing Systems
- Step 1: Automate Data Flows
Connect your ERP’s inventory module to your cash-flow forecasting tool—no manual exports. - Step 2: Set Alerts
Trigger notifications when DSI or turnover ratios deviate beyond thresholds, so finance can adjust forecasts immediately. - Step 3: Monthly Review
Reconcile forecast vs. actual cash usage tied to inventory changes; refine purchase and payment calendars.
By embedding inventory accounting metrics and processes into your cash-flow planning, you’ll unlock more predictable working capital, avoid liquidity crunches, and make strategic purchase decisions with confidence.
Implementation Roadmap for Accounting for Inventory
Bringing all your accounting for inventory strategies to life requires a clear, phased plan. Follow this seven-step roadmap to move from theory to practice—and achieve cleaner books, sharper insights, and healthier cash flow.
Step 1: Conduct a Comprehensive Policy Audit
- What to Do: Inventory all existing processes, from purchase receipts to period-end counts.
- Why It Matters: Identifies gaps—misaligned valuation methods, undocumented write-down triggers, or missing controls—that lead to errors and compliance risks.
- Action Item: Create a simple flowchart of your current state and note pain points.
Step 2: Choose & Document Your Valuation Framework
- What to Do: Select your primary valuation method (FIFO, LIFO*, Average, Specific ID) and any hybrid twists (seasonal layering, lot-based averaging).
- Why It Matters: Formalizing your approach ensures consistency in accounting for inventory, tax planning, and financial reporting.
- Action Item: Draft a one-page policy summary, including formulas, triggers, and examples; file it in your accounting manual.
Step 3: Configure Systems & Controls
- What to Do: Set up your ERP or accounting software to enforce chosen methods. Enable real-time updates (perpetual) or schedule cycle-count modules.
- Why It Matters: Automated controls reduce spreadsheet errors and give finance real-time visibility into stock movements.
- Action Item: In your system, map SKU classes to count frequencies and cost pools; test on a small sample of SKUs.
Step 4: Train Your Teams & Assign Roles
- What to Do: Host hands-on workshops for finance and warehouse staff covering new policies, count procedures, and exception workflows.
- Why It Matters: Engaged, knowledgeable teams drive accurate data capture, reducing shrinkage and reconciliation time.
- Action Item: Appoint “Inventory Champions” per shift to coach peers, audit random SKUs, and escalate anomalies.
Step 5: Pilot & Measure Key Metrics
- What to Do: Run a 30- to 60-day pilot in one warehouse or product line, applying new valuation, counting, and analytics processes.
- Why It Matters: A controlled trial surfaces unforeseen issues—data gaps, system bugs, or training needs—before full rollout.
- Action Item: Track Inventory Turnover, DSI, Accuracy Rate, and Shrinkage weekly; compare against baseline KPIs.
Step 6: Refine & Scale
- What to Do: Analyze pilot results, update procedures, and tweak system settings. Then expand to additional locations or product families.
- Why It Matters: Continuous improvement embeds best practices and builds confidence across the organization.
- Action Item: Hold a “lessons learned” session with cross-functional stakeholders; finalize updated policy doc.
Step 7: Monitor, Report & Iterate
- What to Do: Establish a monthly review rhythm—finance, operations, and leadership examine dashboard insights and audit findings.
- Why It Matters: Ongoing oversight ensures your accounting for inventory remains accurate, agile, and aligned with business goals.
- Action Item: Publish a brief “Inventory Health Scorecard” each month highlighting trends, successes, and action areas.
By following this practical, CashFlow-optimized roadmap, you’ll transform inventory accounting from a periodic chore into a continuous strategic advantage—driving accuracy, compliance, and cash-flow performance across your business.
Step-by-Step Guide: Recording Inventory Accounting in a Ledger and in QuickBooks
Managing inventory accurately isn’t just about keeping count — it’s about ensuring every movement of goods is reflected in your books. Below is a practical, easy-to-follow walkthrough for both manual ledger accounting and QuickBooks, so you can choose the method that works best for your business.
A. Manual Ledger Method
This traditional approach is still used by small businesses and as a backup system.
1. Set Up Your Accounts
- Create the following ledger accounts:
- Inventory (Asset)
- Accounts Payable (Liability)
- Cost of Goods Sold (COGS) (Expense)
- Sales Revenue (Income)
2. Recording a Purchase
- Debit Inventory for the cost of goods purchased.
- Credit Accounts Payable (or Cash) for the same amount.
Example:
Purchased $5,000 worth of goods from Supplier A on credit.
Entry:
Inventory (Debit) – $5,000
Accounts Payable (Credit) – $5,000
3. Recording a Sale
- Debit Accounts Receivable (or Cash) for the sale amount.
- Credit Sales Revenue for the same amount.
- Then, record the cost of goods sold:
- Debit COGS
- Credit Inventory
Example:
Sold goods worth $8,000 that cost $3,000 to acquire.
Entry 1: Accounts Receivable (Debit) – $8,000
Sales Revenue (Credit) – $8,000
Entry 2: COGS (Debit) – $3,000
Inventory (Credit) – $3,000
4. Period-End Adjustments
- Conduct a physical count.
- Adjust Inventory and COGS to match actual quantities.
B. QuickBooks Method
QuickBooks automates much of the process but still requires correct setup.
1. Enable Inventory Tracking
- In QuickBooks, go to Settings > Account and Settings > Sales.
- Turn on Track Inventory Quantity on Hand.
2. Add Your Inventory Items
- Go to Sales > Products and Services > New.
- Choose Inventory type.
- Enter:
- Item name/description
- Initial quantity on hand
- Purchase cost
- Sales price
- Preferred vendor
3. Recording a Purchase
- Use + New > Bill (or Expense if paying immediately).
- Select the inventory item(s), quantity, and purchase cost.
- QuickBooks will automatically increase the Inventory Asset account.
4. Recording a Sale
- Use + New > Invoice (or Sales Receipt).
- Select the inventory item sold.
- QuickBooks will:
- Reduce Inventory Asset
- Record COGS
- Record Sales Revenue
5. Performing Inventory Adjustments
- Go to + New > Inventory Qty Adjustment for shrinkage, spoilage, or write-offs.
Pro Tip:
If you handle seasonal inventory or large product catalogs, consider integrating QuickBooks with inventory management software for real-time tracking and automated reordering.
Real-World Examples: How Inventory Accounting Works in Practice
Example 1: Seasonal Retail Business — Tracking Fashion Inventory
A mid-sized clothing retailer (let’s call them TrendWave Apparel) experiences high stock turnover in spring and autumn due to seasonal launches.
Before adopting proper inventory accounting, TrendWave struggled with overstock after each season, tying up working capital.
How Inventory Accounting Helped:
- They switched from a simple periodic system to a perpetual inventory system using weighted average cost.
- This allowed them to update COGS in real time and make quick pricing decisions for end-of-season clearance.
Sample Journal Entry — Recording Inventory Purchase
Purchased 500 jackets @ $50 each on credit from supplier “Alpha Textiles”
| Date | Account | Debit | Credit |
|---|---|---|---|
| 2025-03-05 | Inventory – Jackets | 25,000 | |
| Accounts Payable – Alpha | 25,000 |
Result: Overstock reduced by 18%, freeing up $14,000 in cash flow for the next buying cycle.
Example 2: Food Distributor — Managing Expiry Dates
A regional food distributor (FreshFlow Foods) deals with perishable items. Inventory accounting is critical for managing FIFO and ensuring expiring goods are sold first.
Challenge:
Before 2024, their manual tracking led to 4% product write-offs monthly due to missed expiry dates.
Solution:
They integrated a FIFO-based perpetual system linked to barcode scanning. Each purchase batch’s expiry date is recorded, and the system automatically pushes older batches into promotions before newer ones.
Sample Journal Entry — Writing Off Expired Goods
Expired goods worth $1,200 removed from inventory
| Date | Account | Debit | Credit |
|---|---|---|---|
| 2025-06-28 | Loss on Inventory Write-off | 1,200 | |
| Inventory – Perishables | 1,200 |
Result: Write-off rate dropped to 1%, saving around $27,000 annually.
Key Takeaway
Real-world inventory accounting isn’t just about compliance — it directly affects profitability and cash flow. Whether you’re managing seasonal stock or perishable goods, applying the right accounting method and tracking system can turn hidden losses into measurable gains.
Common Pitfalls & How to Avoid Them in Accounting for Inventory
Even the best accounting for inventory plans can stumble if you fall into familiar traps. Below are the top pitfalls—and proven tactics to sidestep them.
1. Relying Solely on Spreadsheets
Pitfall: Manual spreadsheets invite data-entry errors, broken formulas, and version-control chaos—leading to misstated ending inventory and COGS.
Avoidance Strategy:
- Move to a Perpetual System: Adopt an ERP or inventory module with built-in costing and cycle-count support.
- Hybrid Backup: If full ERP isn’t feasible, schedule automated nightly imports from your spreadsheet into a simple database tool (e.g., Airtable, Google BigQuery) to catch anomalies.
- Pro Tip: Lock key formula cells and use data validation rules to reduce typos if you must use spreadsheets.
2. Ignoring Slow-Moving & Obsolete Stock
Pitfall: Letting outdated SKUs linger inflates your balance sheet, ties up cash, and risks larger write-downs later.
Avoidance Strategy:
- Regular Obsolescence Reviews: Quarterly, run an SKU “health report” sorting by last sale date and turnover ratio.
- Automatic Alerts: Configure your system to flag SKUs with zero movement for X days (e.g., 180 days) and prompt a markdown or write-down decision.
3. Misaligned Cutoff Procedures
Pitfall: Recording freight-in, returns, or transfers in the wrong period skews both ending inventory and COGS, violating the matching principle.
Avoidance Strategy:
- Standardize Cutoff Policies: Clearly document when to record goods in transit, returns, and intercompany transfers.
- Train & Audit: Include cutoff rules in your onboarding bootcamp and sample transactions each month to verify compliance.
4. Overlooking Ancillary Costs
Pitfall: Excluding handling, duties, or overhead from your inventory value underreports assets and understates COGS when sold.
Avoidance Strategy:
- Comprehensive Cost Capture: Use purchase order workflows that require freight and duty fields to be completed before you can close the PO.
- Allocate Overhead: Implement a simple percentage-based overhead loading (e.g., 10% of unit cost) if detailed tracking isn’t possible.
5. Inconsistent Valuation Application
Pitfall: Applying different valuation methods across warehouses or product lines without policy leads to audit red flags and incomparable financials.
Avoidance Strategy:
- Unified Policy Manual: Maintain one valuation framework—and any hybrid tweaks—with step-by-step instructions.
- System Enforcement: Configure your ERP to prevent SKU-level override of the approved method.
6. Skipping Team Engagement
Pitfall: Ignoring frontline feedback and training means staff revert to old habits—undermining process improvements.
Avoidance Strategy:
- Inventory Champions: Empower warehouse liaisons to surface issues and co-design solutions.
- Feedback Loop: Host monthly “Count & Cash” huddles to discuss data insights, celebrate wins, and address pain points.
7. Failing to Monitor Key Metrics
Pitfall: Without regular KPI reviews (turnover, DSI, accuracy), you miss early warning signs of shrinkage or overstock.
Avoidance Strategy:
- Dashboard Alerts: Set threshold triggers—e.g., turnover below 4x/year or accuracy below 99%—that email finance leads automatically.
- Monthly Scorecards: Distribute a one-page “Inventory Health Report” to stakeholders, highlighting trends and action plans.
By proactively addressing these common inventory accounting pitfalls, you’ll maintain cleaner records, stronger controls, and more reliable financial insights—keeping your business agile and audit-ready.
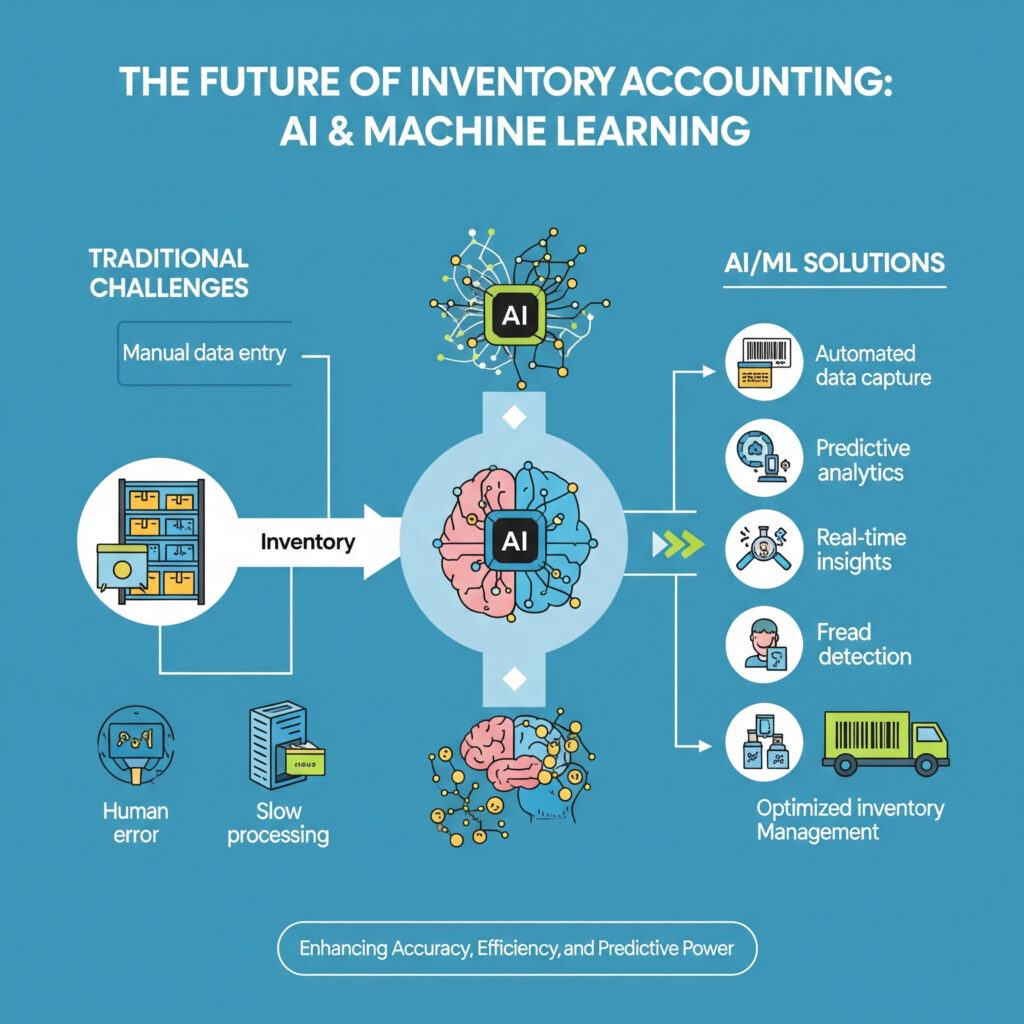
The Future of Inventory Accounting: AI & Machine Learning
The world of inventory accounting is quickly moving beyond manual spreadsheets and delayed reporting. Artificial Intelligence (AI) and Machine Learning (ML) are no longer “upcoming” technologies — they are already transforming how businesses track, value, and manage inventory in real time.
From Challenges to Smart Solutions
In the past, inventory accounting faced common bottlenecks:
- Manual data entry that slowed down workflows and increased mistakes
- Human error in stock counts and transaction records
- Slow processing that delayed important business decisions
AI-powered systems now turn these pain points into opportunities:
- Automated data capture using barcodes, RFID, and image recognition
- Predictive analytics to forecast demand, pricing trends, and reorder points
- Real-time insights to make faster, more informed decisions
- Fraud detection by spotting unusual transaction patterns
- Optimized inventory management to maintain ideal stock levels and reduce waste
The result is greater accuracy, faster decision-making, and improved cash flow.
The Numbers That Prove the Change
Market data shows just how significant this shift is:
- The global AI in inventory management market is projected to grow from $9.6 billion in 2025 to $27.2 billion by 2030 (SuperAGI, 2025).
- Businesses using AI-led inventory optimization have achieved:
- ~15% fewer stockouts
- ~20% lower carrying costs
- 5–8% better service levels (Blue Ridge Global).
- AI forecasting has increased accuracy by 20–50% and reduced lost sales by up to 65% (Blue Ridge Global).
- Retailers like Target have expanded AI-driven inventory coverage to over 40% of their product assortment, more than double from two years earlier (Business Insider, 2025).
Why This Matters for Your Business
AI in inventory accounting isn’t about replacing people — it’s about giving teams the tools to work smarter. By automating routine tasks and delivering predictive insights, businesses can:
- Free up working capital by reducing excess inventory
- React faster to supply chain changes and demand shifts
- Lower operational costs while improving customer satisfaction
The takeaway is simple: AI and ML are turning inventory accounting into a proactive, strategic function. Businesses that adopt these tools early will be positioned to stay ahead in efficiency, accuracy, and profitability.
Conclusion & Next Steps
Congratulations—you’ve now mastered the essential pillars of accounting for inventory, from core concepts and valuation methods to controls, tax strategies, and cash-flow alignment. Here’s how to turn insights into action:
- Recap Core Takeaways
- Inventory is both an asset and a driver of expense—get your cost flows right to protect margins.
- Choose and document the valuation method that best fits your cost dynamics, and consider innovative hybrids like seasonal layering or lot-based averaging.
- Embed risk-based cycle counts, gamified shrinkage prevention, and real-time analytics to maintain 99%+ accuracy.
- Optimize tax and compliance with strategic write-downs, clear IFRS/GAAP policies, and robust audit documentation.
- Align inventory KPIs (DSI, turnover, GMROI) with your cash-flow forecasts to keep working capital lean.
- Your 3-Point Action Plan
- Download the “Inventory Accounting Playbook”
Grab our free, step-by-step PDF template—complete with cycle-count calendars, KPI dashboards, and policy outlines—to fast-track your implementation. - Run a 30-Day Pilot
Select one product line or warehouse zone. Apply your new valuation method, count schedule, and analytics dashboard. Measure improvements in accuracy, turnover, and cash-flow forecasts. - Scale & Iterate Monthly
Roll out refined processes across all locations. Convene a monthly “Inventory Health” meeting to review scorecards, share wins, and tackle any emerging gaps.
- Download the “Inventory Accounting Playbook”
- Stay Connected
- Subscribe for Updates: Get fresh tips on accounting for inventory and working-capital management delivered to your inbox.
- Join Our Webinar: Reserve your spot for an in-depth demo of inventory controls and analytics best practices.
- Contact Our Experts: Have questions about your unique setup? Schedule a personalized consultation with our inventory accounting specialists.
By following these next steps, you’ll transform inventory accounting from a compliance necessity into a strategic advantage—fueling profitability, optimizing cash flow, and preparing your business for scalable growth.
Frequently Asked Questions (FAQs)
1. What are the main inventory accounting systems?
There are two main systems:
- Perpetual inventory system – Updates inventory records in real time whenever sales or purchases happen. It’s accurate and fast but requires good software and scanning tools.
- Periodic inventory system – Updates inventory records only at set times, like month-end. It’s simpler to run but gives less up-to-date information.
2. What inventory valuation methods can I use?
The three most common are:
- FIFO (First-In, First-Out) – The oldest stock costs are used first when calculating the cost of goods sold.
- LIFO (Last-In, First-Out) – The newest stock costs are used first.
- Weighted Average – All items are given an average cost, which works well for products that are alike or interchangeable.
3. How does inventory management affect my cash flow?
When you buy inventory, your cash is tied up until the items are sold. Holding too much stock can slow down cash flow, while efficient inventory control helps you free up money for other business needs. Selling stock quickly and avoiding overstocking keeps your cash moving.
4. Which metrics should I track to monitor my inventory performance?
Some useful ones are:
- Inventory turnover – How often you sell and replace your stock in a set period.
- Days inventory outstanding (DIO) – How many days, on average, it takes to sell your inventory.
- Cash conversion cycle – How long it takes to turn your inventory into cash in hand.
5. What is cycle counting, and how is it different from a full physical count?
Cycle counting is a method where you count small sections of your inventory regularly instead of doing a full warehouse count at once. This way, you keep track of accuracy without stopping operations for a big audit.
6. Why is accurate inventory accounting so important?
Your inventory numbers feed directly into your financial statements. If they’re wrong, your profits, taxes, and decision-making will all be affected. Accurate accounting also helps you spot problems early, like stock losses or slow-moving products.
Found this helpful? Share it:
Inventory Accounting ( Accounting for inventory ) is a term for the systems and methods used to track, value, and report a…
Inventory Accounting ( Accounting for inventory ) is a term for the systems and methods used to track, value, and report a…
Inventory Accounting ( Accounting for inventory ) is a term for the systems and methods used to track, value, and report a…